Stablecoins vs Yield Bearing Stablecoins: The Two Types That Matter
MAY 7, 2025 • 5 MIN READ

Not all stablecoins are the same. In practice, stablecoins serve two core purposes:
Moving money → payment stablecoins
Growing money → yield stablecoins
This simple distinction is by no means exhaustive, yet it is helpful and can be illuminating for many. It should guide how we design for adoption, user experience, regulation, and use cases. Other, more robust classifications (by collateral, peg mechanism, decentralization, or regulatory status) still matter. However, none of them reflect the user-facing function.
Stablecoins are widely seen as crypto’s breakout use case. But to scale, we need a more user-centric framework. You shouldn’t buy coffee with your yield vault. Combining both types in one category (as many dashboards do) is like storing your paycheck in a hedge fund: technically possible, but it doesn’t make too much sense.
Of course, the line isn’t always clean. Stablecoins can play either role, and every design carries its own risks. Here, I zoom in on the primary user purpose. We can refine the distinction to make it a bit less simplistic:
- 💳 Payment-first stablecoin: keeps the peg as closely as possible; aims for instant spend and cheap settlement; usually, yield stays with the issuer; still can be lent out for yield in lending markets; optimizes for simplicity. Non yield bearing stablecoins are typically backed by high-quality liquid reserves such as cash equivalents, short-term Treasuries, or government money market funds, and do not pay interest to holders. These non yield bearing stablecoins are designed for price stability and liquidity, in contrast to bearing stablecoins and yield bearing stablecoins that pass on yield to holders.
- 📈 Yield-first stablecoin: still targets the peg, but usually passes yield from a specific yield strategy to the holder; usually held, not spent; many exotic designs available. Yield mechanisms such as lending platforms, liquidity pools, and yield farming on decentralized exchanges (DEXs) enable stablecoin holders to generate yield, with smart contracts automating the process and protocol revenue, trading fees, and transaction fees supporting the stablecoin yield.
As said, stablecoins can role-flip from payments to yield and vice versa. Still, the payments vs yield can help unlock smarter UX, clearer regulation, and easier adoption. It’s the same peg (usually), but a different purpose.
This simple framework uses a market-driven lens. It starts with how people actually use stablecoins, not with code or statute. Regulators already echo the split: think the U.S. GENIUS Act’s “payment stablecoins”. Builders, like my favorite Sky where I’ve been involved for years, separate USDS (spend/payments) from sUSDS (yield).
What might we gain from the payments vs yield split?
- Better risk frameworks.
Yield-bearing coins should be measured by: yield source and its health, strategy concentration, redemption/exit risk, peg resilience, use of leverage, protocol exposure, among others. Payment coins require more focus on peg stability, market depth and liquidity, redemption mechanics, reserve quality and transparency, issuer risk. One-size-fits-all metrics don’t work. Additionally, liquidity risk, market stress, and counterparty exposure are key considerations for yield-bearing coins, as these risks can be exacerbated during volatile markets or high demand periods, potentially leading to liquidity shortages in secondary markets and impacting the ability to redeem or exit positions.
- Retail adoption.
This distinction matches TradFi mental models and reduces user confusion and error. New users shouldn’t unknowingly hold complex yield tokens. Yield bearing stablecoins are emerging as digital analogs to traditional money market funds and money markets, offering digital assets that generate income and referencing familiar concepts from traditional finance. The growth in stablecoin transaction volumes and market cap further highlights their increasing role in the stablecoin market.
- Better UX.
Providers like wallets should avoid confusing users by mixing up payments and yield stablecoins. This will unlock a simpler and smarter wallet UX. Sophisticated users know the difference perfectly, but proper labels should be presented in the UX to make it clear even for newbies. This will also make integration easier for neobanks and other fintechs. Of course, the real UX hurdle is not just labeling, but educating on tail risk. Clear labeling for non yield bearing and yield bearing stablecoins is essential, as token holders benefit from passive income, token rewards, and staking rewards in DeFi ecosystems. Communicating the opportunity cost of holding non yield bearing assets is also important for user decision-making.
- Institutional adoption.
Yield/payment distinction aligns with existing financial categories, improves accounting and risk segregation, and supports regulatory clarity. Regulatory compliance is critical for institutional adoption, and participants should seek investment advice and consult a qualified financial advisor before investing in yield bearing tokens or participating in liquidity provision and other DeFi strategies.
- Better regulation.
Payment and yield stablecoins will be regulated differently. These products have different risk profiles and the regulators will naturally distinguish between them. It’s not an accident that payments and investments (securities, most generally speaking) are subject to almost entirely different regulatory regimes everywhere. Lawmakers are already moving in this direction: the GENIUS Act bill in the US and MiCAR in the EU recognize this. It does not mean that some payment stablecoins could never offer yield (as debated in the context of the GENIUS Act bill), but it’d be like a savings account among a wide range of investment products. It is also important to distinguish between algorithmic stablecoins and collateral-backed stablecoins, as the former carry unique risks, and to ensure regulatory compliance for tokenized money funds and digital assets.
This isn’t a perfect model (far from it). But it’s the simplest way to orient product, users, and policy around purpose. Some of the drawbacks:
- Yield is a complex category that encompasses various subtypes. They vary in terms of structure, risks, and use cases. Some lend into DeFi, some stake ETH; others buy Treasuries. It’s hard to disagree that this is a (big) umbrella term, and one can expect changes over time as the market matures and—especially—regulators get to it. It’s possible that over time, the concept of “yield stablecoin” will lose sense as it unbundles into more specific and clear categories. Yields vary depending on market conditions, interest rates, trading volume, and the total value locked in liquidity pools, and net yield or net yields are affected by transaction fees and protocol revenue, making the real return for liquidity providers and token holders dynamic and sometimes complex to calculate.
- Who earns the yield? If yield is not passed to the users, there is some other actor getting it (usually, the issuer). As mentioned, stablecoins can migrate from “issuer-yield” to “holder-yield.” Also, stablecoin users can earn yield in lending markets and it is not yet certain if yield stablecoins are sufficiently distinct from the secondary yield sources from the user perspective. In DeFi, borrowers pay interest and make interest payments to liquidity providers and token holders, with these flows managed by smart contracts that automate the distribution of protocol revenue and stablecoin yield.
- Some argue we should call this broader group “yield tokens,” not “yield stablecoins.” That’s fair. But in practice, yield stablecoins have emerged as a distinct subclass with stable pegs and specific user roles. They often are treated as a separate category from, for instance, non-stablecoin tokenized RWAs, LSTs (liquid stake tokens), or different DeFi structured yield products. We’ll see how this trend develops over time, as the boundaries are often blurred, such as with rebasing yield stablecoins.
- Payment stablecoins might someday offer yield. Regulation will define those boundaries. MiCAR forbids it. The GENIUS Act debates it. The market will adapt accordingly.
These concerns are real. Still, it’s unhelpful to talk about “stablecoins” as one thing. The payment vs yield split is foundational and overdue. Let’s label it clearly and build around it. If your stablecoin does not fit into either category easily, also make it clear.
More research is needed, especially on assets that blur the line (like rebasing tokens) or live outside it (like non-stable yield tokens and tokenized RWAs). The impact of abundant liquidity, liquidity mining campaigns, and liquidity mining on the stablecoin market is significant, as these mechanisms can drive adoption and affect yield opportunities. Additionally, emerging markets and cross border payments are major drivers of stablecoin adoption, especially in regions where fiat currency is less stable or access to traditional finance is limited.
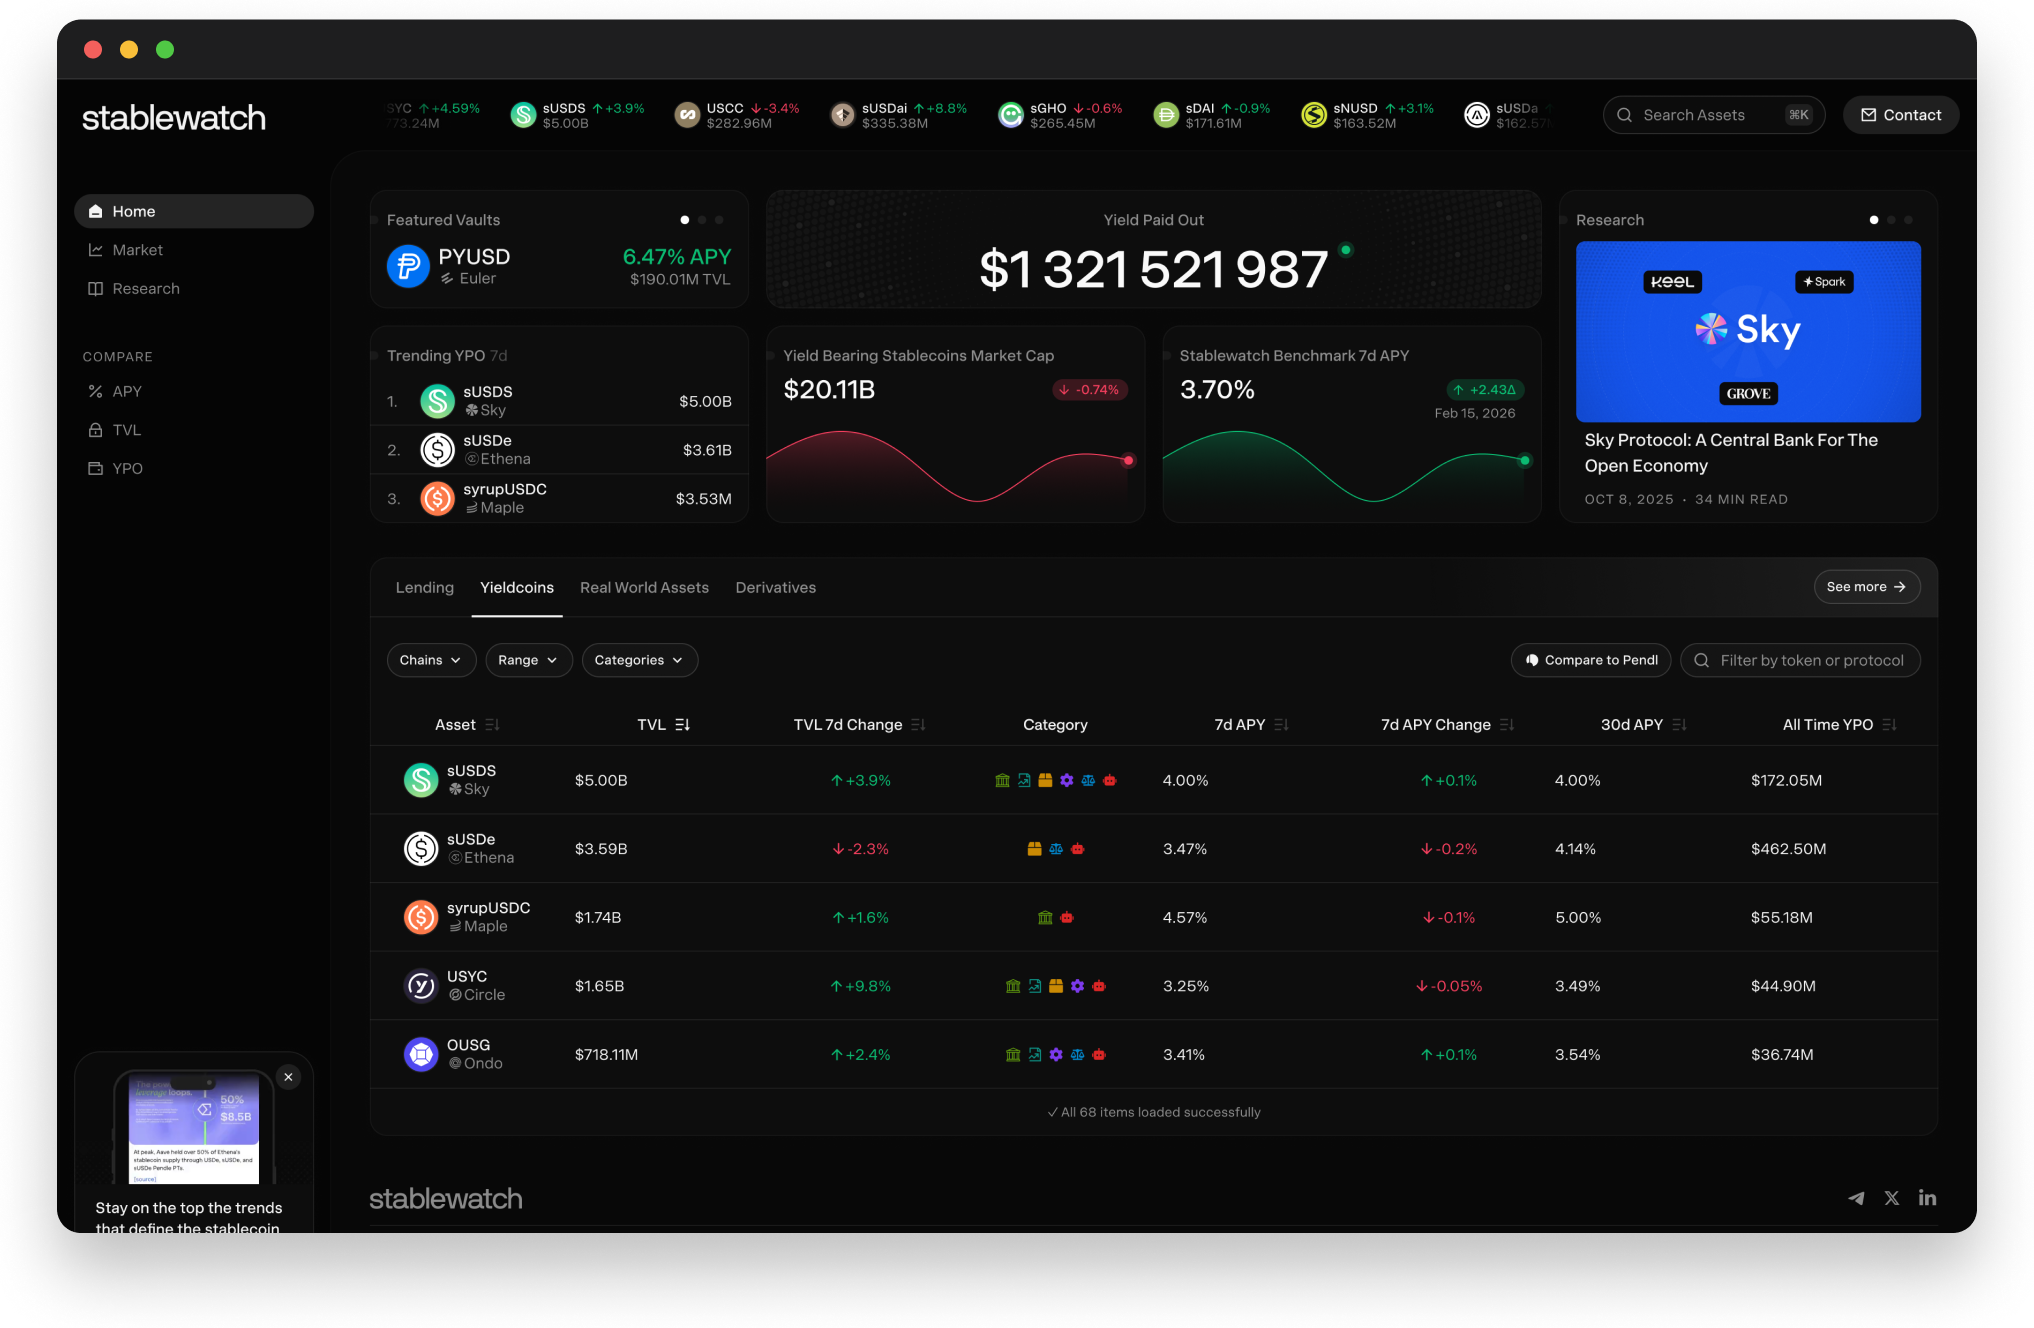
Keep an eye on stablewatch.io and our Twitter accountfor deeper data and clearer classifications, and especially the upcoming work on the stablecoin risk assessment framework.
Author
Jacek Czarnecki
Jacek Czarnecki
Enjoyed this read? There's more.
Get Stables Weekly, our free newsletter covering the latest stablecoin market trends and insights. Delivered to your inbox every Friday.